Gold's Round Trip: A January Record, Then a Long Slide
Bullion peaked near $5,600 an ounce in late January before giving back a substantial share of that gain, even as it holds roughly 30% above where it traded a year ago.
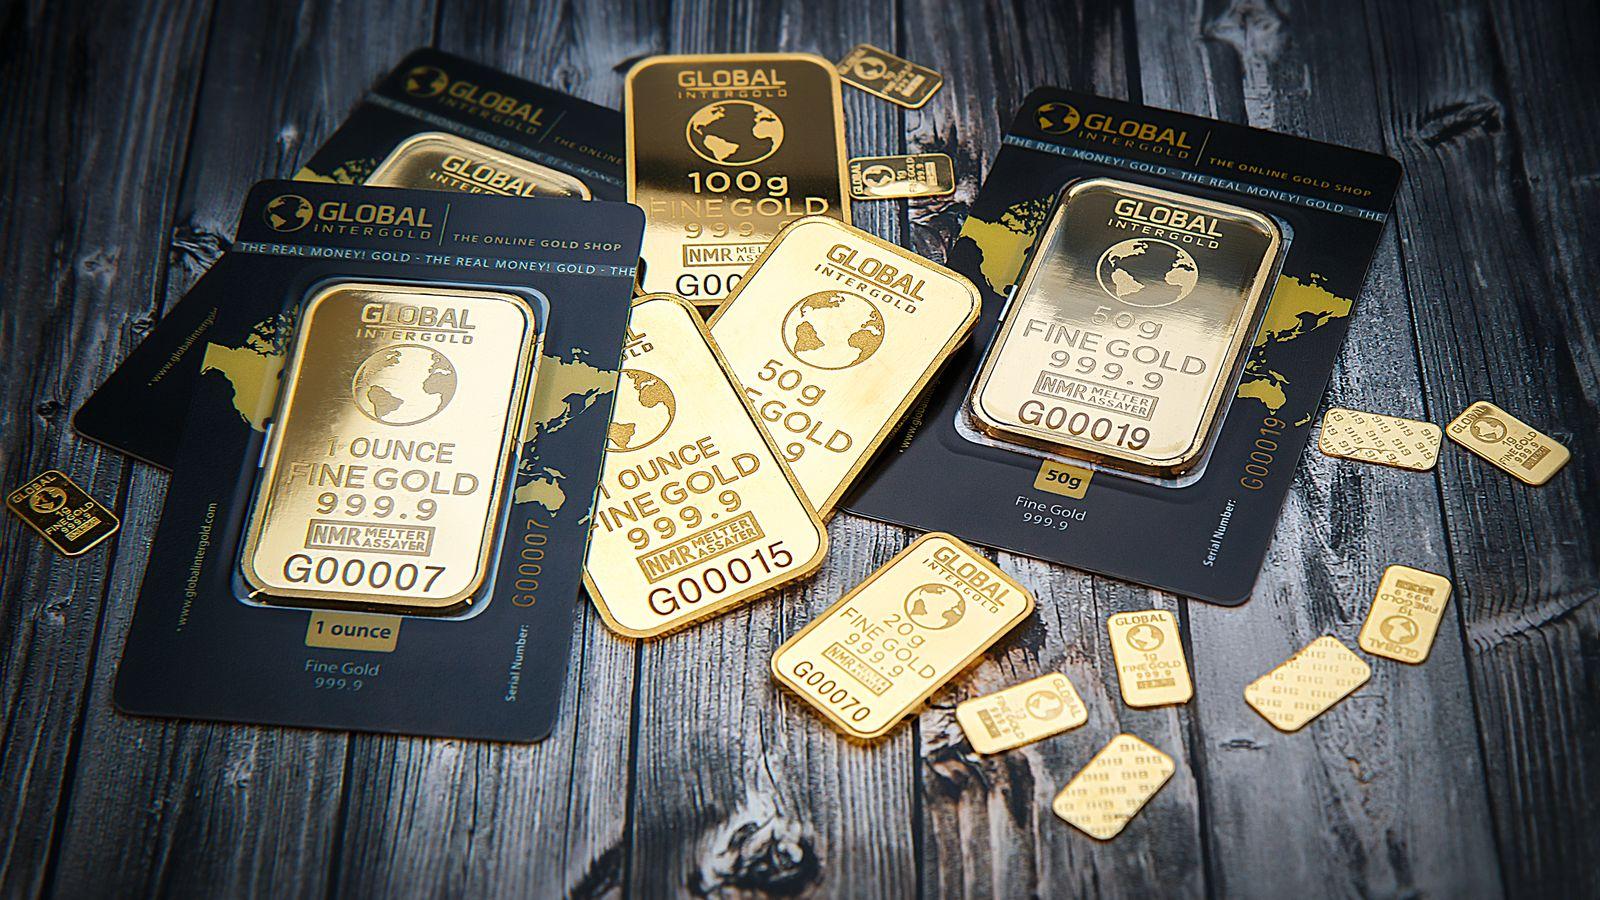
Gold had already been the trade of the decade before this year began. In January it went vertical, reaching a record around $5,597 an ounce on the 29th, and then it did what parabolic moves usually do.
Bullion has since retraced a substantial portion of that spike, trading in the mid-$4,000s through the summer. Measured year over year, it remains up roughly 30%.
What drove the peak
Three forces converged in January. Central banks — particularly in Asia — had been accumulating reserves for several years, a structural bid unrelated to price. Geopolitical risk was rising in multiple theaters. And investors were positioning for a Federal Reserve that had just cut rates three times.
Then the picture changed. The Fed stopped cutting. Long-term Treasury yields rose toward 4.75%, raising the opportunity cost of holding an asset that pays nothing. And an energy shock made real assets tied to production more attractive than a metal held for insurance.
The signal in the level
The instinct is to read the pullback as a verdict on inflation risk. That reading is too simple. Gold at the mid-$4,000s is still priced far above anything seen before this decade, and the buyers who have driven the structural bid — central banks diversifying reserves away from dollar assets — do not trade on quarterly momentum.
That behavior fits with the dollar's own performance: the currency has drifted near multi-month lows against major peers even as U.S. yields rose, which is a combination that suggests investors want compensation for holding dollar claims rather than fewer of them.
Where it sits in a portfolio
For most investors, the practical question is whether gold has done its job. It rose sharply into a period of geopolitical stress, provided a hedge when equity markets fell in March, and has given back part of the gain as conditions stabilized.
That is roughly what an insurance asset is supposed to do. The mistake is treating it as a growth position — which is exactly what the January spike tempted a great many buyers into doing.